


Speciality food ingredients sector report 2026: clean label, health, and science-led IP drive record M&A
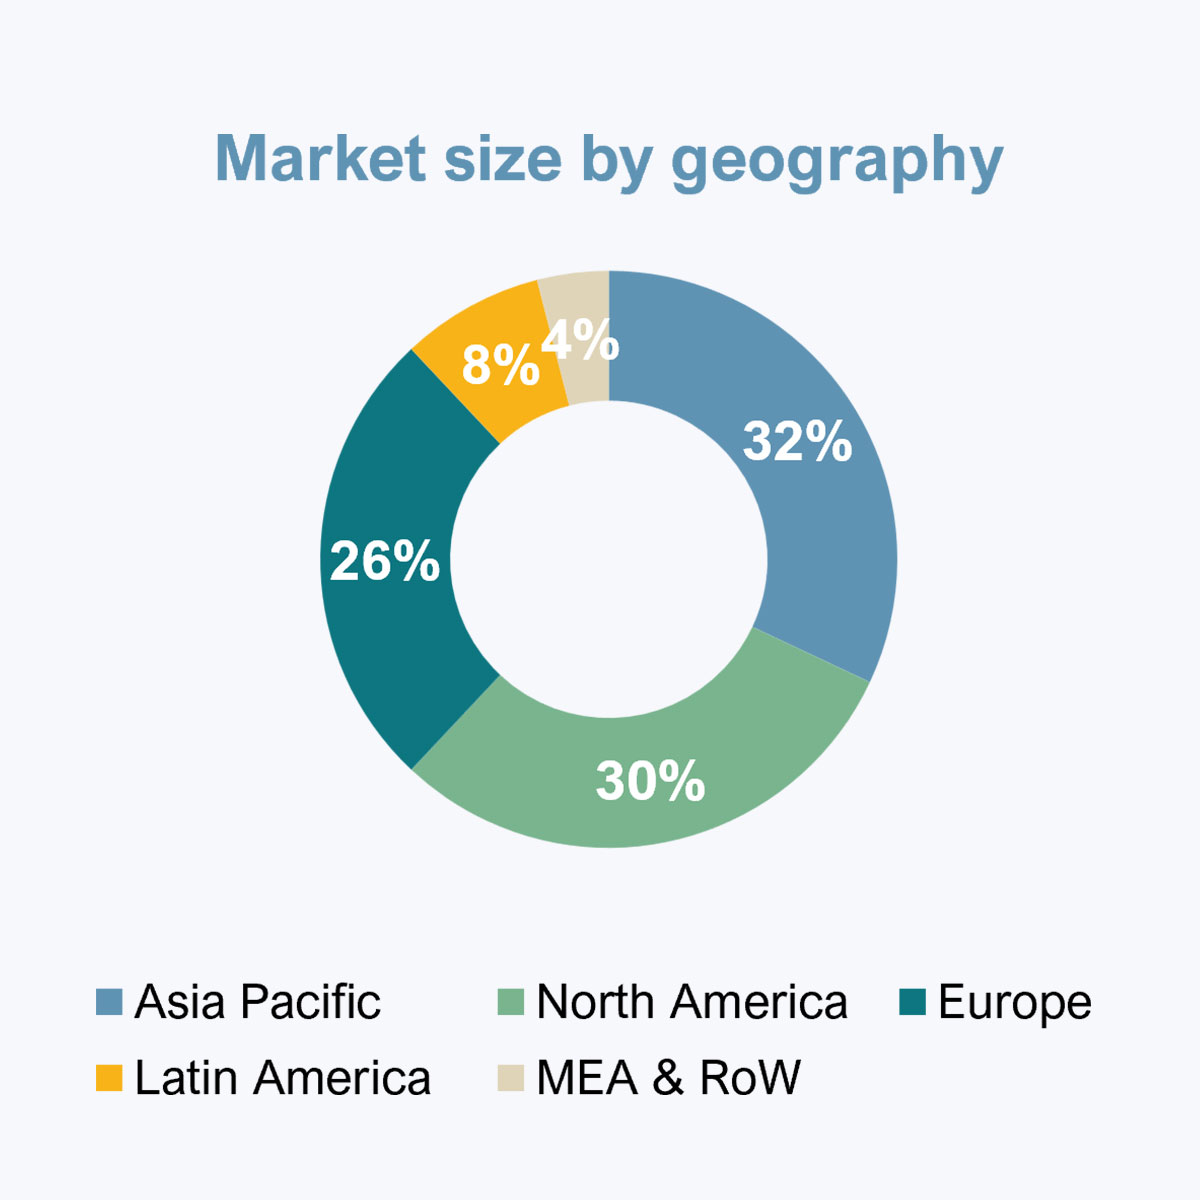
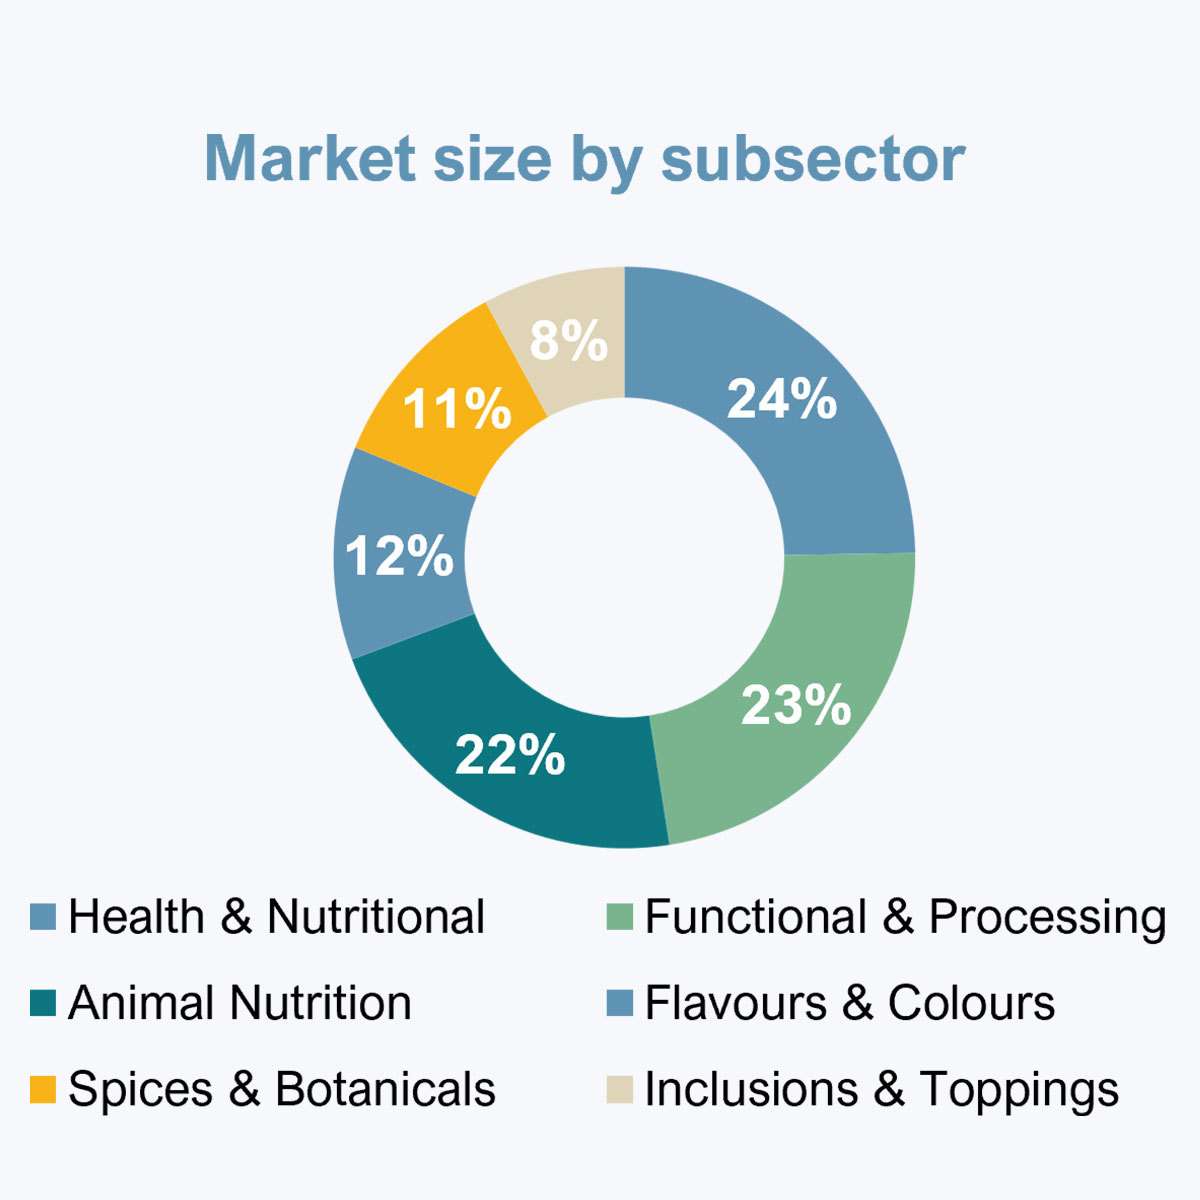
Clairfield’s speciality food ingredients report maps a GBP 163 billion global market growing at around 5.5% a year, roughly twice the pace of the wider food market. The report covers market structure across six subsectors, the trends shaping demand, trading multiples, and recent strategic and private equity transactions.
Key takeaways
Market overview and trends

Speciality ingredients make up 30% to 40% of the total food ingredients market by value and capture the majority of its growth and M&A activity. The shift to natural and clean-label formulations, rising demand for health-functional foods, and premiumisation across end markets all drive demand. Health and nutritional ingredients form the largest and fastest-growing subsector, expanding at 7% to 8% a year, with gut health, protein, and personalised nutrition leading the way.
Regulation is also speeding up reformulation: the US FDA’s planned phase-out of petroleum-based synthetic dyes is making natural colours a baseline requirement. Asia Pacific is the largest and fastest-growing region.

Valuation drivers
Leading ingredients companies often achieve EBITDA margins above 20%. Speciality ingredients typically account for less than 10% of a finished product’s cost while determining how it performs, so manufacturers rarely switch suppliers and long-term relationships are the norm.
Acquirors reserve their highest premiums for proprietary IP such as clinically validated strains, patented fermentation processes, and natural sourcing capabilities.
Recent M&A transactions
The European food ingredients sector has recorded more than 300 transactions since 2019, and 2025 set a new record for deal volume. Crossborder deals account for over 65% of activity, with European buyers particularly active in North America.
Transaction multiples have consistently risen above 10x EV/EBITDA. Private equity remains a major force, using buy-and-build strategies to consolidate fragmented subsectors.
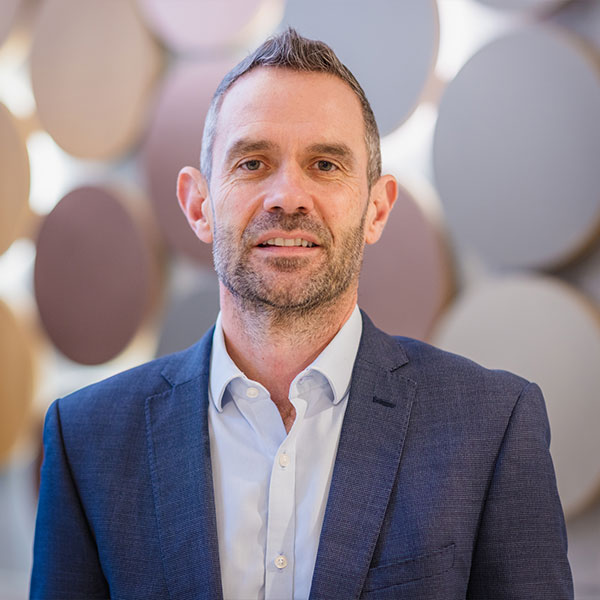
“Speciality ingredients sit upstream of almost every consumer trend, from clean label to gut health and protein. Each subsector remains fragmented, and we expect strategic buyers and private equity to keep competing for well-run, founder-owned businesses with proprietary formulations and loyal customers.”
Gary Ecob, Partner, Clairfield in the UK
Download the full report here:

